Growth Navigate Funding: Global Executive Summary
Growth navigate funding is a critical dual-purpose concept in the international venture ecosystem. Strategically, it describes the structured methodology global founders use to navigate growth-stage capital options, balancing institutional venture capital, venture debt, and revenue-based financing to minimize cap table dilution. Commercially, it refers to specialized advisory firms such as Growth Navigate Funding (growthnavigatefunding.net) that partner with founders across the United States, United Kingdom, Europe, and international tech hubs. These advisory firms prepare investor-grade pitch decks, engineer dynamic financial models, organize data rooms, and facilitate warm introductions to qualified global venture funds and angel networks. Successful execution requires aligning annual recurring revenue (ARR), gross margins, and cash runway with the appropriate capital instrument.
Key Takeaways for Global Founders
- Worldwide Scope: The framework addresses cross-border fundraising dynamics across North America, the UK, Europe, and global emerging technology ecosystems.
- Cap Table Preservation: Blending non-dilutive capital (revenue-based financing, venture debt, innovation grants) enables founders to preserve 12% to 18% more equity through Series A.
- Institutional Due Diligence: Global venture firms reject over 85% of opportunities during initial screening due to flawed unit economics, unrealistic growth models, or unverified data rooms.
- Advisory Acceleration: Dedicated fundraising advisory teams reduce round closure cycles from six months to 90 days by managing investor targeting and institutional materials.
- Instrument Alignment: Utilizing standardized frameworks like Y Combinator SAFE notes in the US and Advanced Subscription Agreements in the UK prevents premature valuation lock-in.
According to research published by the National Venture Capital Association and global market intelligence from the British Business Bank annual equity report, global venture funding surpassed $340 billion, yet more than 65 percent of founders reported significant friction in identifying the appropriate capital structure for their development stage. Raising capital in 2026 has transformed into a global, cross-border discipline requiring operators to weigh international currency exposure, valuation benchmarks, and governance terms.
Whether evaluating specialized advisory partners or architecting an internal capitalization plan, mastering how to growth navigate funding decisions is essential for long-term viability. Surrendering excessive equity during early rounds permanently impairs founder upside, while mismanaging debt service covenants can jeopardize operational independence.
This comprehensive global guide deconstructs the Growth Navigate Funding methodology, reviews the services provided by specialized fundraising platforms, and details an actionable roadmap for securing capital from Pre-Seed to expansion equity across international markets.
What Is Growth Navigate Funding? The Strategic Concept & Global Advisory Platform
For international founders and executive teams, the term encompasses two complementary pillars:
- The Universal Growth Methodology: Navigating growth funding is the systematic process of sequencing capital instruments to match a company’s real-world traction. It guides a startup from initial founder bootstrapping and angel syndicates through venture capital, venture debt, and mezzanine financing, ensuring equity dilution remains disciplined at every milestone.
- The Advisory Firm (growthnavigatefunding.net): As a commercial entity, Growth Navigate Funding operates as an international fundraising consultancy. The firm collaborates with startups across the US, UK, Canada, and European tech hubs from Pre-Seed through Series C. Its advisory suite encompasses fundraising roadmap development, investor-grade pitch deck design, financial modeling, and structured introductions to a proprietary network of over 1,000 active institutional venture capital funds, family offices, and corporate venture capital (CVC) partners.
In an environment where institutional allocators demand proven capital efficiency, relying on informal pitch materials is no longer viable. Partnering with seasoned advisors or adopting institutional-grade preparation allows founders to stand out in crowded international deal pipelines.
The Global 4-Stage Capital Roadmap: Pre-Seed to Series B
Capital benchmarks vary by geographic market, but institutional expectations follow universal milestones. The table below outlines standard round sizes, instruments, and qualification metrics across the US, UK, and international tech ecosystems.
| Funding Stage | Typical Global Range (USD / GBP) | Primary Capital Sources | Target Milestones & Criteria |
|---|---|---|---|
| Pre-Seed | $100,000 – $500,000 (£75,000 – £400,000) |
Founders, Angels, Accelerators, SAFE / SEIS | Functional prototype or MVP, initial beta customer feedback, founding team alignment |
| Seed Stage | $1,000,000 – $3,500,000 (£800,000 – £2,800,000) |
Seed VC Funds, Angel Syndicates, Family Offices | Early ARR ($20K – $80K MRR), clear user retention cohorts, documented go-to-market motion |
| Series A | $5,000,000 – $15,000,000 (£4,000,000 – £12,000,000) |
Institutional Tier-1 & Tier-2 Venture Capital | $1.5M – $4M ARR, demonstrated product-market fit, sustainable unit economics (LTV/CAC > 3.5) |
| Series B & Venture Debt | $15,000,000 – $40,000,000+ (£12,000,000 – £32,000,000+) |
Growth Equity Funds, Specialized Venture Lenders | Market category leadership, international geographic expansion, predictable net revenue retention |
Stage 1: Pre-Seed and Seed Capitalization
In the United States and global hubs, the standard Pre-Seed instrument is the Simple Agreement for Future Equity (SAFE), popularized by Y Combinator. SAFEs eliminate valuation haggling and legal complexity during early testing. In the UK and Europe, founders often utilize Advanced Subscription Agreements or tap statutory tax schemes like the Seed Enterprise Investment Scheme. The objective at this stage is securing 12 to 18 months of runway to validate market demand without giving up board seats.
Stage 2: Series A Institutional Due Diligence
Series A is where international capital markets demand rigorous proof of scalability. Investors review sales funnel conversion rates, payback periods, and cohort churn. Learning how to find investors in the UK, US, and Europe who actively lead rounds in your sub-sector is vital, as cross-border syndication often brings foreign market access alongside capital.
Stage 3: Growth Equity and Non-Dilutive Venture Debt
Upon reaching significant ARR, founders in major tech hubs increasingly turn to venture debt providers (such as Silicon Valley Bank, Stride, or specialized private credit funds) to supplement priced equity rounds. Venture debt provides non-dilutive liquidity to finance enterprise sales hires or inventory expansion, minimizing founder equity dilution ahead of major liquidity events.
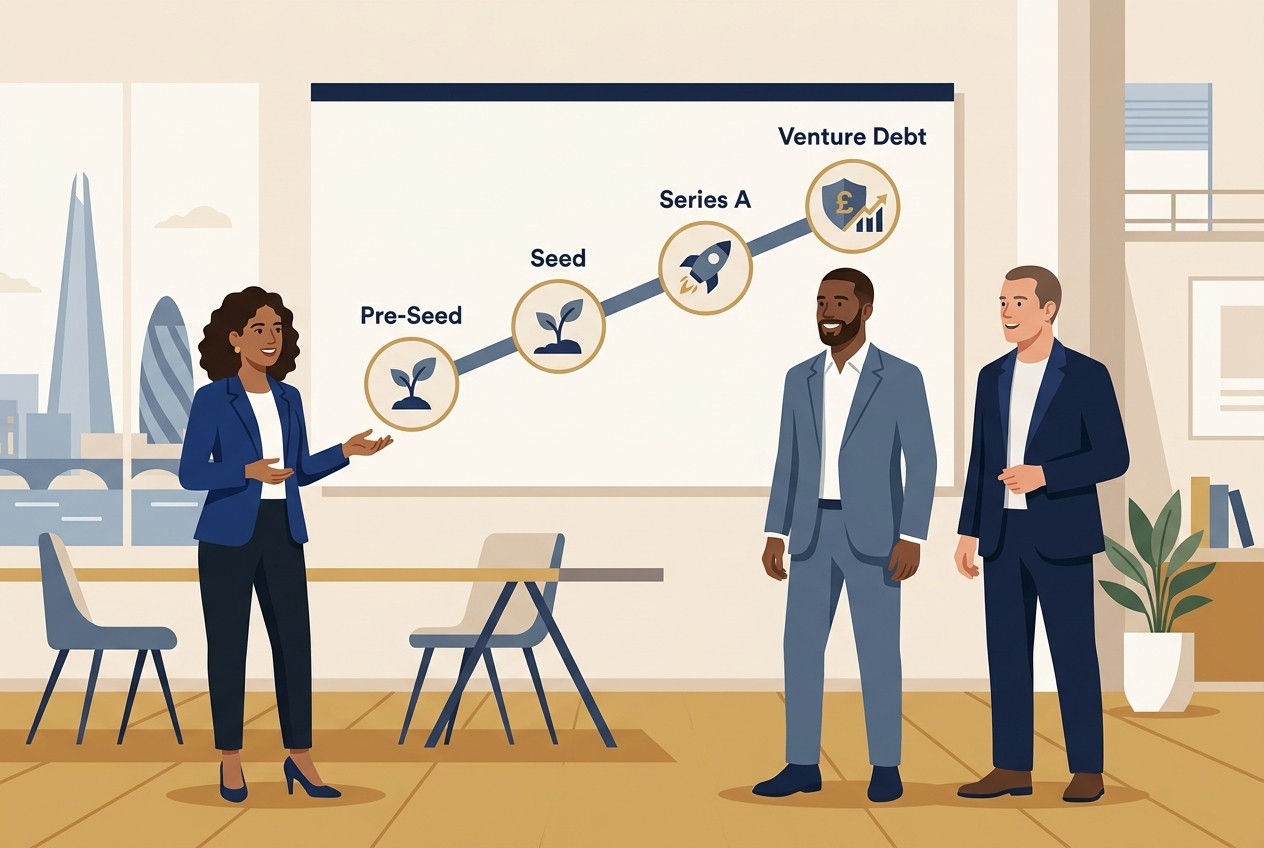
Deconstructing the Growth Navigate Funding Advisory Process
Fundraising is notoriously time-consuming, frequently pulling founders away from product development and customer acquisition for four to six months. Dedicated advisory platforms like Growth Navigate Funding offer a formalized process to streamline this workflow across four stages:
1. Strategic Diagnostic and Market Sizing
Advisors audit historical revenue performance, customer acquisition costs, and total addressable market (TAM) definitions. By stress-testing financial models against institutional benchmarks, advisors identify positioning gaps before engaging outside investors.
2. Investor-Grade Pitch Deck Engineering
Securing investor interest requires an engaging narrative backed by verified data. Professional advisory teams structure decks that satisfy venture partner investment committees, emphasizing gross margins, defensible technology moats, and scalable distribution advantages.
3. Dynamic Financial Modeling and Cap Table Scenarios
Institutional due diligence requires robust 3-statement models reflecting variable hiring projections, burn multiples, and scenario analyses. Establishing an investor-ready model prevents costly valuation re-trades during term sheet negotiations. Operators can examine core techniques in our guide to financial modeling for startups.
4. Targeted Global Introductions and Data Room Preparation
Unsolicited email outreach to venture capital firms yields less than a 1% meeting conversion rate. Advisory programs leverage warm connections across North American and European venture funds, family offices, and corporate venture arms. In parallel, they assemble secure virtual data rooms containing commercial contracts, corporate governance records, and IP assignments to accelerate legal due diligence.
Global Capital Comparison: Equity vs Debt vs Revenue-Based Financing
Every percentage point of equity surrendered early permanently reduces executive ownership at exit. Comparing the primary capital structures allows founders to optimize their funding mix.
| Financing Structure | Typical Dilution Range | Repayment & Cash Flow Impact | Primary Advantages | Governance & Operational Considerations |
|---|---|---|---|---|
| Institutional Venture Capital | 15% – 25% per round | Zero monthly debt payments; returns realized at exit | Substantial growth capital; deep strategic network; talent recruitment support | Permanent equity surrender; board oversight; aggressive growth expectations |
| Venture Debt | 1% – 3% (via equity warrants) | Monthly interest and principal amortization (24 – 48 months) | Extends cash runway without material equity dilution | Typically requires existing institutional equity backing; financial covenants apply |
| Revenue-Based Financing (RBF) | 0% (Completely non-dilutive) | Contractual percentage of monthly gross revenue (4% – 9%) | Rapid automated underwriting; zero board seats; flexible monthly cash impact | Higher effective cost of capital for fast-growing firms; limited to high-margin recurring models |
| Global Angel Syndicates | 8% – 15% | Equity return realized upon acquisition or public listing | Founder-friendly governance; specialized industry guidance; flexible terms | Smaller capital allocations; cap table fragmentation if not pooled under a nominee structure |
According to benchmarking insights from the British Private Equity and Venture Capital Association, technology companies that combine non-dilutive debt with institutional rounds reach Series B with an average of 14% higher founder ownership than companies relying solely on priced equity rounds. When engaging high-net-worth investors across international networks, founders should review structured pitching methodologies in our guide on how to find angel investors.
5 Critical Cross-Border Traps to Avoid When Raising Capital
Fundraising pressure can cause founders to overlook complex cross-border and legal risks. Staying vigilant protects corporate independence.
- Currency and FX Mismatches: Raising institutional capital in USD while maintaining payroll and operations in GBP or EUR exposes the business to foreign exchange volatility. Establish treasury buffers to prevent unexpected runway contraction caused by adverse currency shifts.
- Participating Preferred Liquidation Overhangs: Standard term sheets adhere to 1x non-participating preferred shares. Be cautious of investors demanding “participating preferred” rights, which allow them to reclaim their invested capital before participating pro-rata with ordinary shareholders. This term disproportionately reduces founder returns in mid-sized exits.
- Premature Corporate Inversions: Flipping an entity to a Delaware C-Corp before securing US lead investors can jeopardize local tax incentives (such as Section 1202 QSBS in the US or SEIS/EIS in the UK). Coordinate corporate restructuring with qualified cross-border counsel.
- Unregulated Broker Fee Structures: Legitimate fundraising advisory consultancies work on transparent monthly retainers and performance-linked success fees (typically 2% to 5% of institutional capital raised). Avoid brokers demanding large upfront cash retainers exceeding $15,000 paired with non-dilutable equity percentages.
- Post-Funding Burn Acceleration: Securing a funding round often triggers unchecked hiring and marketing expenditure. Monitor unit economics continuously and model cash reserves using our interactive Business Calculators & Financial Tools.
Frequently Asked Questions
What does growth navigate funding mean for an international startup?
Growth navigate funding describes the strategic process of selecting, sequencing, and securing the right mix of capital (venture equity, venture debt, or revenue financing) to scale a startup without excessive equity dilution. It also refers to specialized advisory firms that assist international founders with pitch decks, financial models, and cross-border investor introductions.
Is Growth Navigate Funding a legitimate advisory firm?
Yes. Growth Navigate Funding (growthnavigatefunding.net) operates as a startup fundraising advisory consultancy supporting founders from Pre-Seed through Series C. The firm provides fundraising roadmaps, pitch deck design, financial model preparation, and warm introductions across a network of over 1,000 institutional venture capital funds, family offices, and angel syndicates.
How do US SAFE notes compare to UK and European investment instruments?
The Simple Agreement for Future Equity (SAFE), pioneered by Y Combinator, is the standard convertible instrument in the US, allowing startups to raise capital without setting an immediate fixed valuation. In the UK and Europe, founders often use Advanced Subscription Agreements (ASAs) or Convertible Loan Notes (CLNs), which provide comparable flexibility while preserving eligibility for statutory angel tax reliefs.
What are the main non-dilutive funding options for growth-stage companies?
The most prevalent non-dilutive options include venture debt lines, revenue-based financing (RBF), working capital facilities, and non-repayable government research and innovation grants. These instruments provide growth capital without forfeiting equity or permanent board seats.
What fee structure is standard for startup fundraising advisory firms?
Reputable advisory firms generally charge a monthly project retainer alongside a success fee ranging between 2% and 5% of institutional capital closed. Founders should avoid intermediaries that demand substantial upfront cash retainers without performance-tied deliverables.
How much equity should an international founding team surrender in a Seed round?
Industry consensus suggests selling between 10% and 20% of company equity during a Seed round. Surrendering more than 25% at Seed leaves insufficient equity for subsequent Series A and Series B rounds, complicating future institutional investment.
Practical Next Steps for Global Founders & CEOs
Executing an international fundraising process requires preparation, clear metrics, and disciplined sequencing. Before initiating investor outreach, complete these four foundational steps:
- Audit Runway and Unit Economics: Calculate your net monthly cash burn, gross margins, and runway duration. Begin fundraising with at least six to eight months of cash reserves to avoid negotiating from weakness.
- Build an Institutional Virtual Data Room: Organize your incorporation documents, capitalization table, employment agreements, and IP assignments in a structured data room to facilitate rapid legal diligence.
- Assess Advisory Partnerships: Evaluate whether your executive team has the bandwidth to run outreach internally or whether partnering with an advisory firm like Growth Navigate Funding will improve narrative polish and investor access.
- Evaluate Term Sheets Holistically: Do not fixate solely on headline valuation. Review governance clauses, liquidation preferences, and information rights with experienced legal counsel before signing exclusivity agreements.