UK businesses secured over £20 billion in ongoing working capital through invoice finance and asset-based lending facilities in 2026, according to official market reporting from UK Finance, supporting more than £315 billion in annual commercial turnover. Yet for growing British enterprises managing 30-day, 60-day, or 90-day payment terms from corporate buyers, unpaid customer invoices remain the single greatest impediment to payroll stability and supplier fulfillment. Partnering with accredited invoice factoring companies allows directors to monetize their outstanding sales ledger immediately rather than waiting months for debtor settlement.
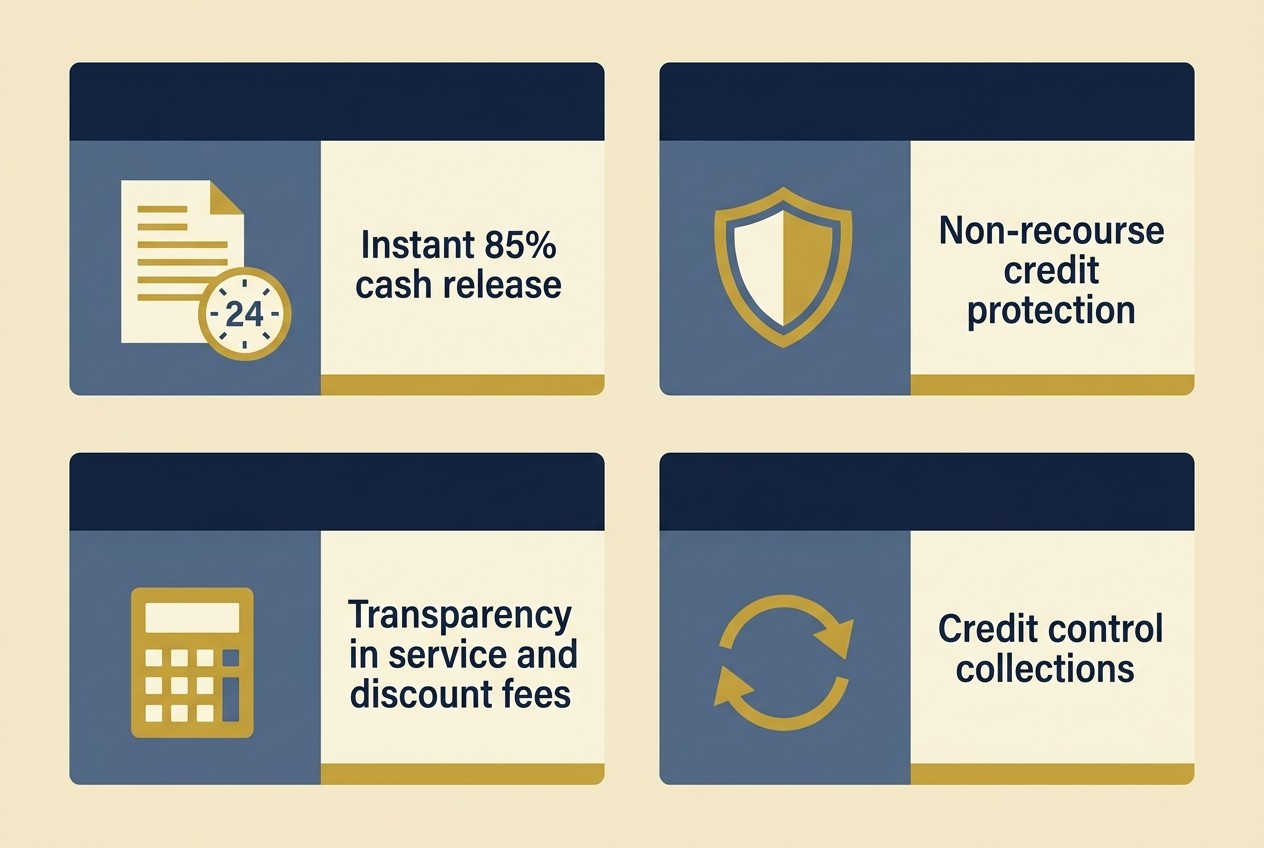
Quick Answer: Invoice factoring companies provide commercial financing by purchasing an enterprise’s outstanding B2B sales invoices, advancing between 80% and 90% of the ledger value within 24 hours of invoice issuance. Unlike traditional bank overdrafts or fixed loans, factoring facilities scale dynamically alongside sales turnover. The factoring company manages credit control, customer payment chasing, and collections directly. Pricing consists of two core components: a service fee (0.5% to 3.0% of turnover for credit control administration) and a discount margin (typically 2.0% to 4.5% above the Bank of England base rate on borrowed capital).
Key Takeaways for Enterprise Decision Makers
- Immediate Cash Release: Factoring converts locked sales invoices into liquid capital within 24 hours, releasing up to 90% of gross invoice values upon customer delivery verification.
- Credit Control Transfer: In disclosed factoring arrangements, the provider assumes professional credit control and chasing duties, which frees internal administrative capacity for operations.
- Recourse vs Non-Recourse Risk: Recourse factoring requires businesses to buy back unpaid invoices after 90 days, whereas non-recourse facilities include bad debt protection shielding the company against debtor insolvency.
- Two-Part Pricing Structure: Total facility costs combine a monthly service fee on total sales turnover and an annualized discount rate calculated daily against drawn funds.
- Contract Scrutiny: Watch for hidden fee clauses, including minimum monthly turnover charges, refactoring fees on aged debts, number-check fees, and lengthy 3 to 6 month termination notice periods.
The Mechanics of Invoice Factoring in the UK
In standard business-to-business commerce, suppliers deliver goods or complete contracted services, issue a VAT invoice, and wait between 30 and 90 days for client accounts payable departments to disburse payment. Recent commercial payment research from the Federation of Small Businesses indicates that over half of British small businesses regularly suffer from late settlement, creating severe working capital bottlenecks.
Invoice factoring fundamentally alters this dynamic. Instead of acting as an informal bank for corporate clients, an enterprise assigns its sales ledger to a specialist commercial lender. The factoring process operates through four distinct stages:
- Invoice Generation & Notice of Assignment: You deliver goods or services to your corporate client and issue the invoice containing a legal Notice of Assignment directing payment to the factoring company’s designated trust account.
- Initial Advance Payment: The factoring provider verifies the invoice and deposits between 80% and 90% of the gross invoice total directly into your business bank account within 24 hours.
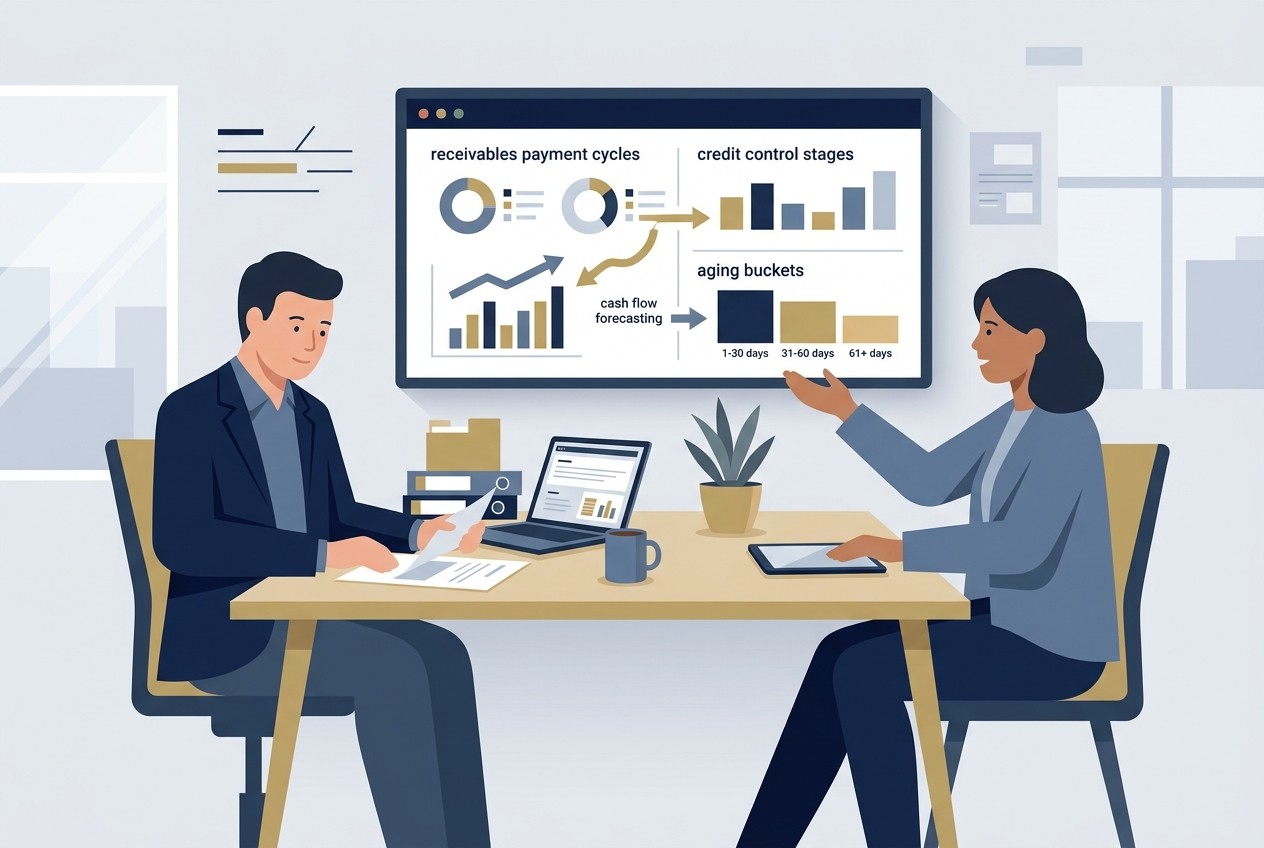
- Credit Control & Collections: The factoring provider’s credit control team manages customer payment chasing, statement distribution, and telephone follow-ups until payment arrives.
- Final Balance Settlement: Once the customer pays the invoice in full, the factoring company releases the remaining 10% to 20% reserve balance to your business, minus agreed service and discount fees.
For organizations seeking to protect operational working capital while planning capital investments like business vehicle finance, factoring ensures liquidity tracks sales expansion without requiring hard real estate debentures.
Factoring vs Invoice Discounting: Choosing the Right Structure
While both mechanisms monetize outstanding accounts receivable, business owners must understand the operational dividing line between factoring and confidential invoice discounting.
The core distinction lies in credit control transparency. In an invoice factoring agreement, the facility is disclosed. Your customers know a third-party finance partner is involved because invoices display an assignment notice, and the factor’s staff communicate directly with debtor accounts teams. This arrangement is ideal for expanding businesses that lack a dedicated internal credit control department.
In contrast, invoice discounting operates confidentially. Your company retains full responsibility for customer collections, your buyers never receive third-party correspondence, and payments flow into a blinded trust account under your company name. However, invoice discounting providers generally demand a minimum annual turnover of £250,000 to £500,000 and proven financial accounting systems before granting approval.
Understanding Factoring Costs, Fees, and Rate Structures
Commercial lenders present fee structures in distinct ways. When comparing quotations, corporate finance officers must evaluate the full fee matrix rather than focusing exclusively on the initial advance rate.
1. The Service Fee (Administration Charge)
The service fee covers credit checking, sales ledger maintenance, debt collection calls, and general platform administration. Providers calculate this fee as a percentage of your total gross invoice turnover passed through the facility, typically ranging from 0.5% to 3.0%. High-turnover businesses with modest customer transaction volumes negotiate rates at the lower end of this scale, whereas high-volume, low-ticket businesses pay higher service percentages.
2. The Discount Margin (Borrowing Charge)
The discount fee represents the interest charged on the capital advanced before the customer settles the bill. It is calculated daily and applied monthly against the drawn balance. Lenders price the discount fee as an agreed margin (usually between 2.0% and 4.5%) pegged to the Bank of England base rate. If you advance £100,000 for 45 days at an annualized discount rate of 7.5% (base rate plus margin), the financing cost for that period equals approximately £924.
3. Credit Protection Surcharge (Non-Recourse Facilities)
If you choose non-recourse factoring, the lender incorporates bad debt insurance. Should an approved customer become legally insolvent before paying, the insurer covers the outstanding balance. Providers charge an additional 0.3% to 1.0% on ledger turnover for non-recourse underwriting.
| Fee Category | Charging Basis | Typical UK Market Range | Strategic Consideration |
|---|---|---|---|
| Service Charge | Percentage of gross sales turnover | 0.50% to 3.00% | Scales with invoice count and debtor ledger complexity |
| Discount Margin | Annualized interest on drawn funds | Base rate + 2.0% to 4.5% | Calculated on daily drawn balances until debtor payment clears |
| Bad Debt Protection | Percentage surcharge on insured invoices | 0.30% to 1.00% | Essential for single-debtor concentrations exceeding 20% |
| Facility Setup Fee | One-off initial onboarding charge | £250 to £1,500 | Covers KYC, legal documentation, and debtor credit audits |
| Minimum Monthly Fee | Fixed floor charge if volume dips | £250 to £1,000 / month | Critical contract clause for seasonal or cyclical businesses |
Top Invoice Factoring Companies in the UK (2026)
The UK factoring marketplace is split between independent specialist institutions, bank-owned commercial finance subsidiaries, and modern digital fintech platforms reviewed in the British Business Bank SME finance review. Below is an objective analysis of the leading providers supporting UK mid-market enterprises.
1. Bibby Financial Services
Bibby Financial Services is the largest independent invoice finance provider in the United Kingdom, supporting over 7,000 small and medium-sized businesses. Operating independently from the high-street clearing banks, Bibby offers high underwriting flexibility for companies experiencing rapid growth, management buyouts, or turnaround situations. They provide both recourse and non-recourse facilities alongside specialized international trade factoring for UK exporters dealing in multiple currencies.
2. Novuna Business Finance
Formerly Hitachi Capital Business Finance, Novuna is consistently recognized for superior customer satisfaction ratings and transparent fee structures. Novuna’s digital interface connects smoothly to popular accounting platforms such as Xero, QuickBooks, and Sage, enabling automatic sales ledger reconciliation. Their factoring products feature competitive service charges and are particularly well suited to professional services, transport, and manufacturing businesses with annual turnovers between £100,000 and £10 million.
3. Close Brothers Commercial Finance
Close Brothers provides bespoke, relationship-driven receivables facilities for larger SMEs and corporate estates generating £500,000 or more in turnover. Known for senior credit underwriting expertise, Close Brothers works closely with businesses in construction, wholesale distribution, and engineering. They excel at tailoring asset-based lending packages that combine invoice factoring with plant, machinery, or property financing.
4. Kriya (Formerly MarketFinance)
Kriya represents the modern digital alternative to traditional factoring houses. Leveraging cloud underwriting algorithms, Kriya allows businesses to choose between selective single-invoice factoring and whole-turnover facilities. Their platform eliminates lengthy physical paperwork, delivering funding decisions in hours and permitting businesses to draw funds on specific high-value customer accounts without pledging their entire customer book.
5. Aldermore Bank
Aldermore Bank operates as a specialist challenger bank offering integrated commercial funding packages. Their invoice factoring division supports growing businesses requiring dedicated credit control assistance combined with structured working capital. Aldermore provides high initial advance rates (up to 90%) and transparent contractual covenants, making them an attractive alternative for businesses dissatisfied with rigid high-street bank restrictions.
| Provider | Maximum Advance Rate | Credit Control Handling | Minimum Annual Turnover | Best Industry Profile |
|---|---|---|---|---|
| Bibby Financial Services | Up to 90% | Full credit control & international collections | £100,000 | Importers, exporters, and fast-growing SMEs |
| Novuna Business Finance | Up to 85% | Automated digital ledger management | £100,000 | Transport, logistics, and manufacturing |
| Close Brothers Commercial | Up to 90% | Dedicated relationship manager & credit control | £500,000 | Mid-market construction, engineering, wholesale |
| Kriya (MarketFinance) | Up to 85% to 90% | Selective credit control or client-managed | £100,000 (selective) | Tech companies, agencies, spot invoice funding |
| Aldermore Bank | Up to 90% | Structured credit control & ledger support | £250,000 | Established SMEs seeking combined asset finance |
Critical Contract Terms and Traps to Avoid
Securing an invoice factoring facility requires examining the master agreement for clauses that can dramatically increase borrowing expenses or restrict commercial freedom.
- Termination Notice Periods: Standard factoring agreements enforce 12 to 24 month minimum terms with mandatory 3 to 6 month written notice windows. If you miss the specific anniversary notification window, the contract automatically rolls over for another full year. Negotiate rolling 30-day or 60-day break clauses after the primary term.
- Refactoring and Aged Debt Penalties: In recourse facilities, if a debtor fails to pay within 90 days of invoice issuance, the factor re-assigns the unpaid invoice back to your business. The advanced capital is deducted from your reserve account, and many lenders assess an aged debt refactoring penalty.
- Concentration Limits: Factors assess risk across your debtor ledger. If one large customer accounts for more than 20% to 30% of your total sales, the factor may restrict funding on invoices exceeding that ceiling unless specific non-recourse credit insurance endorsements are purchased.
- Personal Guarantees and Director Indemnities: While factoring is secured primarily against accounts receivable, lenders standardly require directors to sign personal guarantees or fraud warranties. Ensure guarantees are strictly limited to instances of intentional ledger misrepresentation or phantom invoicing rather than routine commercial debtor failure.
For urgent short-term capital needs that do not warrant pledging your ongoing sales book, evaluating an instant business loan options may provide a simpler, unencumbered funding stopgap.
Frequently Asked Questions
How quickly do invoice factoring companies release cash?
Once your factoring facility is operational and integrated with your accounting software, approved invoice advances are typically deposited into your business bank account within 24 hours of invoice generation and dispatch. Initial facility underwriting and onboarding standardly require between 3 and 10 business days.
What happens if a customer refuses to pay an invoice?
The outcome depends on whether your facility is recourse or non-recourse. Under a recourse factoring agreement, your business remains responsible for unpaid balances; if the debtor fails to settle within 90 days, you must repay the advance or replace it with fresh invoices. Under a non-recourse agreement, the factoring company’s credit insurance absorbs the loss if the debtor enters formal insolvency.
Will my customers know that I am using a factoring company?
Yes. Standard invoice factoring is a disclosed finance facility. Invoices feature a formal Notice of Assignment instructing buyers to pay the factor’s bank account, and the factor’s credit control staff contact customers directly to collect payments. If client-facing confidentiality is essential, businesses should consider confidential invoice discounting instead.
Can startups and new businesses qualify for invoice factoring?
Yes. Unlike traditional bank lenders that require two to three years of audited accounts, invoice factoring companies evaluate the creditworthiness of your commercial customers rather than your balance sheet. As long as you provide verifiable B2B goods or services to creditworthy corporate buyers, newly incorporated businesses can secure factoring facilities.
What is the minimum turnover required for invoice factoring in the UK?
Most independent factoring providers require a minimum annual turnover of £100,000. However, fintech platforms like Kriya provide selective invoice funding with no annual volume commitments, while corporate lenders like Close Brothers focus on businesses generating £500,000 or more in sales.
Can construction businesses use invoice factoring?
Yes, although construction factoring requires specialist underwriters. Because construction contracts involve applications for payment, retentions, and architect sign-offs rather than standard delivery notes, mainstream factors often exclude the sector. Specialist construction factoring providers like Close Brothers and Bibby underwrite uncertified payment applications directly.
How to Structure Your Factoring Facility Tender
Achieving competitive factoring terms requires preparing your financial documentation before approaching commercial lenders. Assemble your last six months of debtor aging schedules, sample customer contracts, credit control procedures, and historical bad debt ratios. Presenting organized ledger data positions your business as an institutional borrower and empowers your team to negotiate discounted service margins.
When reviewing proposals, calculate your total annual effective borrowing rate by modeling both service and discount charges against your projected turnover. Request fee caps on ancillary administrative items, clarify audit schedules, and insist on transparent digital portal reporting. Proactive cash flow management ensures that invoice factoring operates as a predictable engine for enterprise expansion rather than an administrative burden.
Editorial Link Map
| Link Type | Anchor Text | Destination URL | Strategic Purpose |
|---|---|---|---|
| External Citation | market reporting from UK Finance | https://www.ukfinance.org.uk/ | Official UK invoice finance industry advances data (£20B+ funded) |
| External Citation | commercial payment research from the Federation of Small Businesses | https://www.fsb.org.uk/ | Authoritative UK SME late payment statistics and commercial impacts |
| External Citation | British Business Bank SME finance review | https://www.british-business-bank.co.uk/ | UK Government economic bank review on alternative lending markets |
| Internal Link | business vehicle finance | https://elitebusinessjournal.co.uk/business-vehicle-finance-uk-guide/ | Commercial asset management and vehicle fleet financing context |
| Internal Link | confidential invoice discounting | https://elitebusinessjournal.co.uk/invoice-discounting-uk-guide/ | Direct product comparison between factoring and invoice discounting |
| Internal Link | instant business loan options | https://elitebusinessjournal.co.uk/instant-business-loan-uk-guide/ | Short-term working capital alternative to sales ledger pledging |
| Internal Link | cash flow management | https://elitebusinessjournal.co.uk/cash-flow-tips-every-small-business-owner-needs-to-know/ | Operational cash flow principles and working capital governance |