According to annual tourism data published by VisitBritain, domestic holidaymakers and international visitors contribute over £36 billion annually to the British leisure economy, generating sustained demand for self-catering holiday accommodation across national parks, coastal retreats, and cultural hubs. Independent commercial lending figures from the Intermediary Mortgage Lenders Association (IMLA) indicate that specialist short-term rental borrowing has expanded rapidly, with building societies and specialist banks advancing over £2.4 billion in holiday rental facilities. Investors transitioning from traditional buy-to-let to short-term rentals frequently achieve gross yields between 9% and 14%, substantially outperforming standard Assured Shorthold Tenancy (AST) returns.
Operating a holiday let requires specialized commercial debt. Standard residential buy-to-let mortgages explicitly prohibit short-term holiday guests, meaning utilizing standard mortgages for Airbnb or holiday cottage lets breaches loan covenants and risks immediate facility recall. Securing dedicated holiday let mortgages requires navigating seasonal income underwriting, higher deposit requirements, personal usage limits, and fundamental legislative updates to the UK tax code. This guide details how holiday let mortgages operate, how lenders stress-test seasonal receipts, how the abolition of the Furnished Holiday Lettings (FHL) regime impacts profitability, and how to select the right specialist lender.
Quick Answer: What Are Holiday Let Mortgages?
Holiday let mortgages are specialist property loans designed specifically for properties let on a short-term, self-catering basis to holidaymakers and business travellers. Unlike standard buy-to-let mortgages that require fixed 12-month AST agreements, holiday let loans permit daily and weekly guest turnarounds via platforms like Airbnb, Vrbo, and Sykes Cottages. Lenders assess affordability through seasonal rental projections (high, medium, and low season averages over a 30-week annual trading period) validated by an independent letting agent. Most lenders cap borrowing at 70% to 75% Loan-to-Value (LTV), require minimum outside earned income of £25,000 to £40,000, and permit the owner up to 60 days of personal recreational occupancy per year.
Key Takeaways for Holiday Let Investors
- Specialist Products Are Mandatory: Letting a property on Airbnb or short-term platforms using a standard buy-to-let mortgage breaches lending terms, risking loan foreclosure.
- Seasonal Income Stress Testing: Lenders calculate borrowing limits using a 30-week average of low, mid, and peak season weekly tariffs certified by an accredited holiday letting agent.
- Tax Structuring Shift to SPVs: Following the abolition of the separate Furnished Holiday Lettings tax regime, holding assets within a Limited Company Special Purpose Vehicle (SPV) preserves 100% mortgage interest deductibility.
- Personal Use Allowances: Most specialist building societies permit between 30 and 60 days of owner occupation per calendar year, provided peak summer weeks remain available for commercial letting.
- Small Business Rates Relief Opportunity: Meeting statutory letting thresholds (at least 70 days let and 140 days available in England) enables qualifying properties to access 100% Small Business Rates Relief, paying zero council tax or business rates.
Holiday Let vs. Standard Buy-to-Let Mortgages: Key Contrasts
Before exploring product terms, property investors must distinguish between standard residential buy-to-let loans and dedicated holiday rental facilities. While both secure debt against residential property, their legal, operational, and underwriting mechanics differ completely:
| Feature Comparison | Standard Buy-to-Let (AST) | Holiday Let Mortgages |
|---|---|---|
| Permitted Tenancy Structure | Assured Shorthold Tenancies (6 to 36 months) | Short-term holiday licences (days or weeks) |
| Rental Income Assessment | Fixed monthly market rent certified by RICS valuer | Seasonal projections across peak, mid, and low seasons (30-week formula) |
| Maximum Loan-to-Value (LTV) | Up to 75% to 80% | Typically 70% to 75% |
| Owner Personal Use | Strictly prohibited (breaches AST terms) | Permitted up to 30 to 60 days per year |
| Primary Lending Providers | Mainstream high-street banks and retail lenders | Regional building societies and specialist commercial banks |
| Minimum Earned Income Criteria | Often zero minimum for experienced landlords | Typically £25,000 to £40,000 non-rental income |
A frequent error among novice investors is attempting to convert an existing buy-to-let property into an Airbnb without notifying their mortgage provider. Mainstream lenders monitor online portals, council licensing registers, and insurance filings. Operating an unauthorised short let breaches mortgage terms, triggering demand letters, default interest rates, or demands for immediate redemption.
Under statutory Financial Conduct Authority mortgage rules, holiday let mortgages are classified as unregulated commercial lending when held by corporate entities or commercial landlords, though consumer regulations apply if the owner or family members occupy the property for significant durations.
How Lenders Calculate Affordability: Seasonal ICR Stress Testing
Assessing borrowing capacity on a holiday let is more nuanced than evaluating a standard tenancy. Because tourist income fluctuates across the calendar year, lenders cannot rely on a single monthly rental figure.
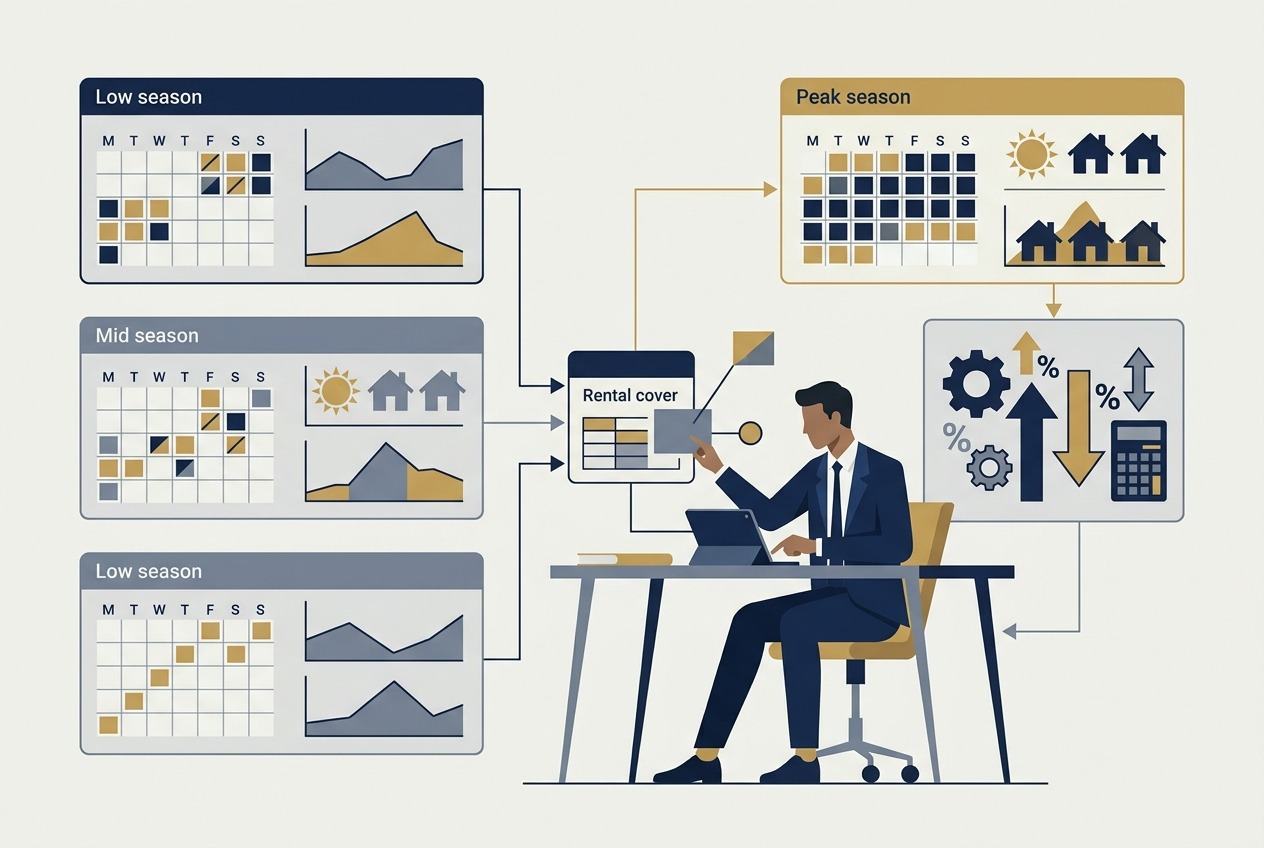
Instead, underwriters require a formal rental forecast letter prepared by an established, independent holiday letting agency (such as Sykes Holiday Cottages, Cottages.com, or a reputable regional letting agent). The agency must forecast weekly gross rental figures across three distinct seasonal tiers:
- High Season (Peak): School summer holidays, bank holidays, and festive weeks (typically 10 to 12 weeks).
- Mid Season: Spring and autumn shoulder months, May half-term, and early autumn (typically 14 to 16 weeks).
- Low Season: Winter trading months outside of Christmas and New Year (typically 24 to 26 weeks).
To establish the annual gross rental baseline, most specialist lenders apply the standard “30-Week Formula”. Rather than assuming a 52-week trading calendar, lenders assume the property generates income for only 30 weeks per year, reflecting seasonal vacancy:
Annual Gross Rental Assessment = (High Season Weekly Rate x 10) + (Mid Season Weekly Rate x 10) + (Low Season Weekly Rate x 10)
Consider a practical calculation. An accredited agency forecasts an £1,800 weekly tariff during peak summer, £1,100 in mid season, and £600 in low season. Applying the 30-week formula yields an annual assessable income of £35,000 (£18,000 + £11,000 + £6,000), or an average monthly income of £2,916.
Once annual income is determined, lenders apply their Interest Cover Ratio (ICR) stress test. For properties held in a personal name by higher-rate taxpayers, lenders typically demand an ICR of 145% at a stress rate of 5.5% to 8.5%. For corporate structures, such as limited company buy to let mortgages, the ICR requirement drops to a more accessible 125%, enabling higher total borrowing against the same rental projection.
Tax Rules: Navigating the Abolition of the FHL Regime
The UK holiday rental sector has undergone its most significant fiscal reform in four decades. Historically, holiday rentals meeting specific occupancy rules qualified under the Furnished Holiday Lettings (FHL) tax regime, granting landlords major tax advantages over standard buy-to-let operators.
Under official GOV.UK furnished holiday lettings tax regime guidance, the separate FHL classification was formally repealed, aligning holiday let tax treatment with traditional residential property businesses. The changes alter how individual property investors calculate tax liabilities:
| Tax Mechanism | Former FHL Regime Rules | Modern Standard Property Rules |
|---|---|---|
| Mortgage Interest Tax Relief | 100% deductible as a business expense against gross income | Restricted to a 20% basic rate tax credit for individual owners (Section 24) |
| Capital Allowances on Fixtures | Full capital allowances on furniture, hot tubs, appliances, and fixtures | Replacement of Domestic Items Relief only; no initial fixture allowances |
| Capital Gains Tax at Disposal | Business Asset Disposal Relief (BADR) eligible at 10% rate | Standard residential CGT rates (18% basic / 24% higher rate) |
| Pension Contribution Basis | Net rental profits counted as relevant UK earnings for pension relief | Rental income classified as passive investment; excluded from pension limits |
The elimination of full mortgage interest deductibility under Section 24 has accelerated incorporation. When an individual higher-rate taxpayer holds a £300,000 holiday let mortgage at 6% interest (£18,000 annual interest), Section 24 restricts their tax relief to just 20% (£3,600), creating significant phantom profit tax liabilities.
Conversely, holding holiday lets within a Limited Company Special Purpose Vehicle (SPV) maintains 100% mortgage interest deductibility as an allowable commercial trading expense. Corporate owners pay Corporation Tax (19% to 25%) only on net profits, while deploying proven corporate reducing UK corporation tax measures, including director pension contributions and capital allowances.
Council Tax vs. Business Rates: The SBRR Opportunity
One major financial advantage of operating a commercial holiday let is the opportunity to be assessed for Business Rates rather than domestic Council Tax.
According to statutory criteria enforced by the Valuation Office Agency holiday let business rates, a self-catering property in England must satisfy two strict operational occupancy tests to transfer from the domestic Council Tax list onto the local rating list:
- Availability Threshold: The property must be available to let commercially as self-catering accommodation for short periods totaling at least 140 days in the previous 12 months, and planned for at least 140 days in the coming year.
- Actual Letting Threshold: The property must actually be let commercially for short periods totaling at least 70 days in the previous 12 months. (In Wales, thresholds are substantially higher, requiring 252 days available and 182 days actually let).
Once transferred to the business rating list, properties with a rateable value under £12,000 qualify for 100% Small Business Rates Relief (SBRR), provided the owner holds only one commercial property in England. Because most single holiday cottages have rateable values below £12,000, qualifying owners pay zero business rates and zero council tax, saving between £1,500 and £3,500 per year compared to domestic properties.
Top UK Holiday Let Mortgage Lenders: Comparison Matrix
Mainstream clearing banks (such as HSBC, Barclays, and Lloyds) do not offer specialist holiday let mortgages directly to individual retail landlords. The UK holiday rental lending market is dominated by mutual building societies and specialist boutique commercial banks:
| Lender Name | Max LTV | Min Earned Income | Personal Use Cap | Notable Product Features |
|---|---|---|---|---|
| Principality Building Society | 75% | £20,000 | Up to 60 days per year | Strong regional appetite across Wales and England; permits Airbnb lettings |
| Leeds Building Society | 75% | £40,000 joint / £60k total | Up to 42 days per year | Experienced pioneer in holiday finance; competitive 2-year and 5-year fixed products |
| Cumberland Building Society | 75% | Underwritten on case merits | Flexible (off-peak only) | Direct end-to-end commercial underwriting; strong appetite for Lake District & coastal assets |
| Hodge Bank | 75% | £25,000 | Up to 90 days per year | Most generous personal use allowance; lends to individuals and limited companies |
| Suffolk Building Society | 80% | £25,000 | Up to 60 days per year | Rare 80% LTV product available; manual assessment of complex borrower structures |
| Paragon Bank (Commercial) | 75% | None for portfolio landlords | Strict commercial focus | Leading choice for multi-unit holiday portfolios, holiday complexes, and SPVs |
When selecting a lender, investors must verify property type restrictions. Many building societies refuse properties with restrictive covenants, properties located on holiday parks, timber-framed lodges, or flats in blocks where the leaseholder agreement forbids short lets. If a property features multiple bedrooms let individually to separate parties, it transitions into HMO territory, requiring compliance with HMO property licensing rules.
Pros and Cons of Holiday Let Mortgage Investment
Investing in holiday rentals offers substantial return potential alongside distinct operational obligations:
| Advantages | Disadvantages & Risks |
|---|---|
| Superior Rental Yields: Gross annual yields of 9% to 14% significantly exceed typical 5% buy-to-let averages. | Seasonal Revenue Volatility: Cash flow peaks during summer and school holidays, with winter booking droughts. |
| Personal Holiday Use: Owners can occupy the property for up to 60 days per year for personal family holidays. | High Operating Overheads: Cleaning, linen changeovers, OTA platform commissions (15%–20%), and utilities reduce gross yields. |
| Small Business Rates Exemption: Properties qualifying for business rates can access 100% SBRR, paying zero council tax. | Higher Borrowing Costs: Mortgage interest rates and arrangement fees are 0.5% to 1.5% higher than standard buy-to-let debt. |
| No Tenant Eviction Friction: Guests occupy under short holiday licences; issues with non-paying long-term AST tenants are eliminated. | Local Planning Scrutiny: Rising council restrictions, registration schemes, and tourist tax levies in tourism hotspots. |
Frequently Asked Questions
Can you get a holiday let mortgage on a standard residential property?
Yes. You can purchase or refinance any standard freehold or long-leasehold residential property with a holiday let mortgage, provided the building meets lender criteria and there are no legal covenants prohibiting holiday letting. However, you cannot use a standard residential or buy-to-let mortgage; you must secure a dedicated holiday let mortgage.
Can I live in my holiday let property permanently?
No. Holiday let mortgage contracts explicitly prohibit the borrower or their immediate family from occupying the property as their permanent primary residence. Lenders typically limit owner usage to between 30 and 60 days per year for temporary recreational breaks. Residing in the property permanently breaches the commercial lending contract and can trigger immediate loan redemption.
How much deposit is needed for a holiday let mortgage?
Most holiday let mortgage providers require a minimum cash deposit of 25%, representing a maximum 75% Loan-to-Value (LTV). While a few specialist building societies offer up to 80% LTV, borrowing at this higher threshold involves stricter income requirements and higher interest margins. Investors purchasing additional residential property must also factor in the higher Stamp Duty Land Tax (SDLT) surcharge.
What documents do lenders require to prove holiday rental income?
For a newly acquired property or a property without holiday trading records, lenders require a formal rental projection letter from an accredited, independent holiday letting agency (such as Sykes Cottages or a local RICS agent). The letter must detail projected weekly rental income across high, mid, and low seasons. For existing operational holiday lets, lenders review the past two years of audited business trading accounts or booking software records.
Can first-time buyers get a holiday let mortgage?
Securing a holiday let mortgage as a first-time buyer is challenging. The majority of specialist building societies require applicants to already own their own residential home, and many require at least 12 months of landlord experience. However, a small number of boutique building societies consider first-time buyers on a case-by-case basis if the applicant possesses strong earned income and substantial cash reserves.
Do I need planning permission to run a holiday let?
In most parts of England, renting a property as a short-term holiday let does not require planning permission if the building remains in the C3 residential use class. However, in Greater London, the 90-day rule restricts short lets without planning consent. Furthermore, local authorities in popular holiday regions (such as Cornwall, the Lake District, and parts of Wales and Scotland) increasingly require planning permission or mandatory registration for short-term holiday lets.
What to Do Next: Your Holiday Let Financing Checklist
Securing holiday rental finance requires thorough preparation before submitting formal applications. Prospective borrowers should complete the following four steps:
- Obtain Professional Seasonal Rental Forecasts: Contact at least two established, recognised holiday letting agencies operating in your target locality. Secure formal written projections detailing weekly tariffs across peak, shoulder, and low seasons.
- Confirm Title Deeds and Leasehold Covenants: Instruct your property solicitor to examine the title deeds for restrictive covenants. If the property is leasehold, ensure the headlease permits short-term commercial letting and holiday accommodation.
- Decide on Ownership Structure (Personal vs. SPV): Consult a chartered tax adviser or property accountant to model whether purchasing in your personal name or via an incorporated Special Purpose Vehicle delivers superior post-tax cash returns following FHL tax reforms.
Financing holiday accommodation is a specialised commercial discipline. Pair experienced broker advice with professional lettings management to build a resilient, high-yielding holiday rental portfolio.