According to market analysis from property consultancy Hamptons based on Companies House filings, there are now more than 469,000 active buy-to-let limited companies registered across the United Kingdom, up from just 91,278 a decade ago. Data indicates that between 75% and 80% of all new residential buy-to-let purchases are now conducted through corporate structures rather than personal names. This structural shift reflects a permanent transformation in how UK property investors fund and manage residential portfolios.
The primary catalyst behind this corporate migration was Section 24 of the Finance Act 2015, which removed the ability for individual landlords to deduct mortgage interest from rental turnover before calculating personal income tax. By financing rental acquisitions through a limited company mortgage, property investors bypass Section 24 restrictions, deducting 100% of mortgage finance costs as allowable business expenses before paying Corporation Tax. However, corporate mortgages carry distinct underwriting hurdles, higher arrangement fees, and mandatory director guarantees that every investor must evaluate before incorporating.
Quick Answer: What Is a Limited Company Mortgage in the UK?
A limited company mortgage is a commercial property loan issued to a UK private limited company, usually established as a Special Purpose Vehicle (SPV), to purchase or remortgage residential buy-to-let properties. Unlike individual buy-to-let mortgages, the limited company can deduct 100% of mortgage interest against rental income as a commercial trading expense, paying Corporation Tax (19% to 25%) solely on net profits. Lenders apply a more generous Interest Coverage Ratio (ICR) stress test to SPVs, typically requiring rental income to cover 125% of mortgage interest at a 5.0% to 5.5% stressed rate, compared to 145% or 165% for individual higher-rate taxpayers. Mortgages require personal guarantees from company directors holding over 20% to 25% equity.
Key Takeaways for UK Property Investors
- Limited company property holdings escape Section 24, allowing full mortgage interest deduction against Corporation Tax.
- Mortgage lenders require a dedicated Special Purpose Vehicle (SPV) registered with specific property SIC codes (such as 68209).
- Lenders use a lower 125% rental stress test for SPVs, increasing maximum borrowing power compared to personal applications.
- Interest rates and product arrangement fees are typically 0.5% to 1.5% higher than standard personal buy-to-let mortgages.
- Company directors holding significant shareholdings must sign personal guarantees, remaining personally liable upon loan default.
What Is a Limited Company Mortgage and Why Do Lenders Require an SPV?
A limited company mortgage is a specialist commercial borrowing facility secured against residential or mixed-use property held by an incorporated UK legal entity. While conventional high-street mortgages are assessed against an individual’s personal salary and consumer credit profile, corporate mortgages evaluate the legal company structure, its rental coverage, and the personal standing of its controlling directors.
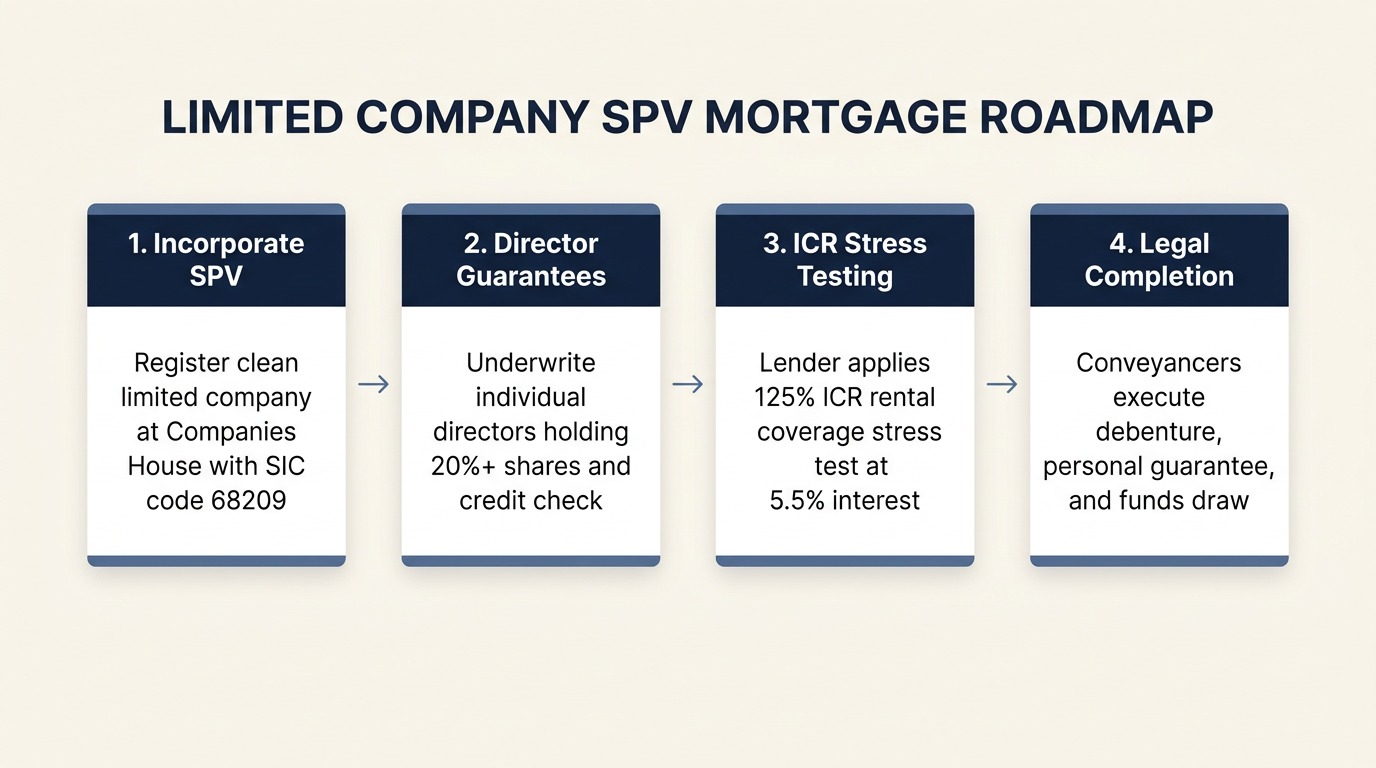
Most specialist mortgage lenders insist that the borrowing entity is structured as a Special Purpose Vehicle (SPV). An SPV is a private limited company incorporated exclusively to buy, hold, and manage property assets. Lenders strongly prefer SPVs over active trading companies because an SPV carries a clean, isolated balance sheet. It has no employees, no trading creditors, no inventory risks, and no exposure to third-party commercial disputes that could trigger insolvency and jeopardize property loan repayments.
Crucial Companies House SIC Codes
When incorporating an SPV at Companies House, selecting the correct Standard Industrial Classification (SIC) code is essential. Specialist mortgage underwriters inspect these codes during initial document screening. If an applicant company lists trading codes associated with consultancy, retail, or building contracting, the mortgage application will be rejected or redirected to expensive commercial trading facilities.
The standard accepted SIC codes for UK property SPVs include:
- 68209: Other letting and operating of own or leased real estate (the industry benchmark for buy-to-let portfolios).
- 68100: Buying and selling of own real estate (used for property trading and refurbishment).
- 68320: Management of real estate on a fee or contract basis (supporting code for block or estate administration).
Limited Company vs Personal Buy-to-Let: The Tax Mechanics
The core motivation for choosing a corporate mortgage structure lies in tax efficiency. Under Section 24 rules, individual landlords cannot deduct mortgage interest from gross rental receipts. Instead, they are taxed on total rental income minus allowable non-finance costs (such as letting agent fees and repairs), receiving a flat 20% tax credit on mortgage interest.
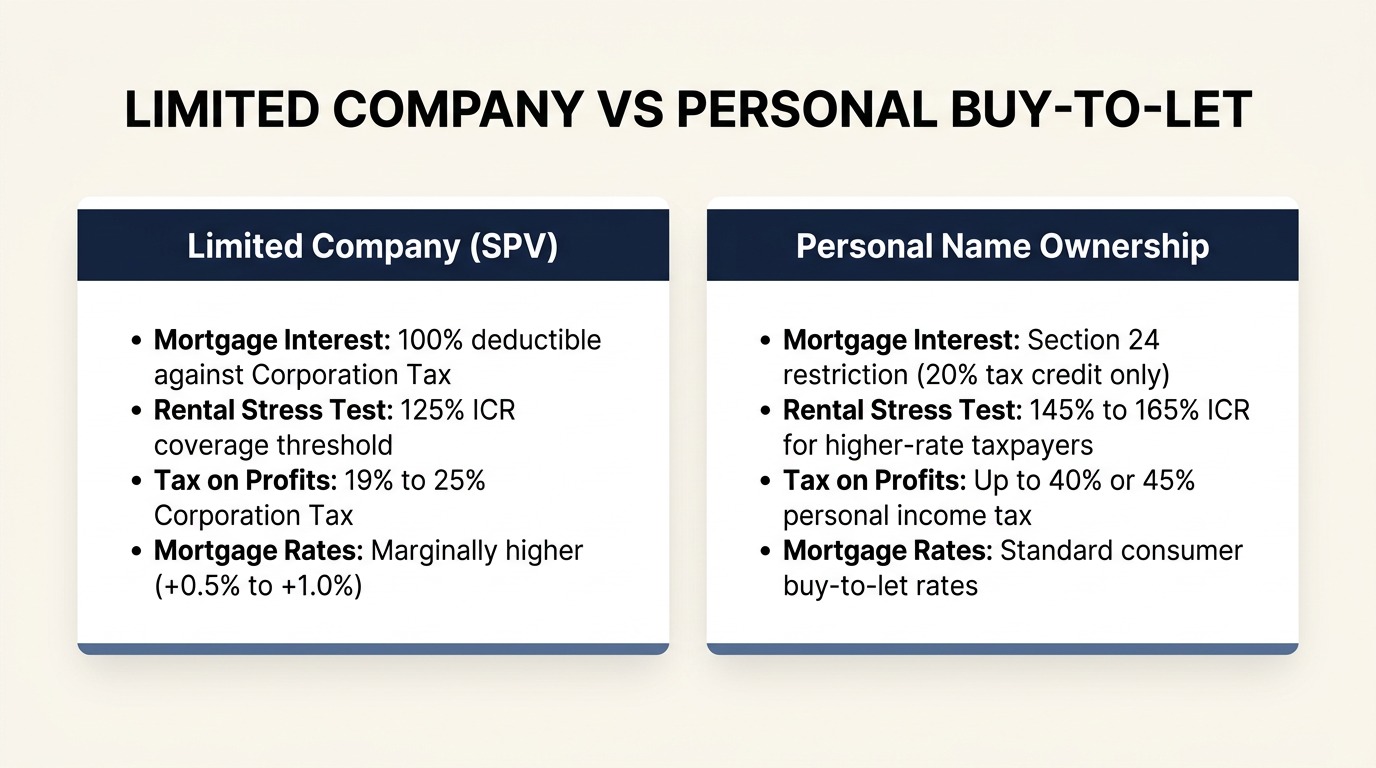
For higher-rate (40%) and additional-rate (45%) taxpayers, Section 24 can generate punitive tax burdens where landlords pay income tax on non-existent economic profits. Inside an SPV, mortgage interest is treated as an ordinary business expense, reducing operating profits prior to Corporation Tax.
According to UK Finance buy-to-let mortgage data, over two-thirds of gross buy-to-let lending value is now routed through corporate vehicles. Investors building multi-property portfolios rely on company structures to reinvest retained gross profits without incurring personal income tax hurdles at every transaction.
Real-World Case Study: The Section 24 Math Breakdown
To see the financial contrast between personal and SPV ownership, consider an investor purchasing a buy-to-let property in Manchester generating £24,000 in annual gross rent with an annual interest-only mortgage cost of £14,000 and £3,000 in letting and maintenance expenses.
Assume the investor is a 40% higher-rate personal taxpayer:
In this representative scenario, holding the asset inside an SPV yields £5,670 in retained profit versus just £1,400 in personal ownership, representing a cash advantage of £4,270 in year one alone. As outlined in official HMRC residential landlord tax guidance, the disallowance of finance deductions applies strictly to individuals, partnerships, and trusts, leaving corporate vehicles entirely unaffected.
Interest Coverage Ratio (ICR) Stress Testing Rules
In addition to tax relief, limited companies benefit from significantly more flexible underwriting rules set under Prudential Regulation Authority underwriting standards.
The Interest Coverage Ratio measures whether the property’s rental income adequately covers mortgage interest payments at a hypothetical stressed interest rate. Because personal landlords pay higher marginal income taxes on their gross rents, mortgage lenders must stress-test personal applications at 145% to 165% of the mortgage payment at a stressed rate of 5.5% or higher.
By contrast, because an SPV pays Corporation Tax at 19% on net profits, lenders apply a standard ICR threshold of 125% at 5.0% or 5.5%. This lower coverage threshold means an SPV can secure higher loan amounts against the exact same rental valuation, reducing the upfront personal equity deposit required from the investor.
The True Costs: Rates, Arrangement Fees & Running Expenses
While the tax advantages of an SPV are compelling, corporate ownership introduces recurring operational expenses that investors must budget for.
1. Mortgage Interest Rate Premium
Specialist commercial lenders fund limited company mortgages from institutional wholesale markets rather than consumer retail deposits. As a result, corporate mortgage rates typically carry a premium of 0.5% to 1.0% above equivalent personal buy-to-let products.
2. High Arrangement and Product Fees
Lenders frequently structure their fees as a percentage of the loan amount rather than flat fees. While standard personal mortgages often feature flat arrangement fees of £995 or £1,495, limited company mortgage fees typically range between 1.5% and 2.5% of the total loan advance. On a £250,000 mortgage, a 2.0% fee equals £5,000, which is normally capitalized onto the loan balance.
3. Annual Corporate Accountancy Costs
Maintaining an active limited company requires statutory annual filings, including preparation of annual accounts, Corporation Tax returns (CT600), Confirmation Statements, and director payroll or dividend administration. Specialized property accounting services generally charge between £800 and £1,800 per year per SPV.
4. Stamp Duty Land Tax (SDLT) Surcharges
When an SPV purchases a residential property, it is subject to the higher residential rates of Stamp Duty Land Tax. Under updated UK tax thresholds, corporate purchases of residential property incur a 5% surcharge on top of standard residential SDLT bands from the very first pound of purchase consideration.
5. Profit Extraction and Dividend Tax
Retaining profits inside the SPV allows full reinvestment into subsequent property acquisitions without tax friction. However, extracting those profits into your private bank account for personal living expenses triggers dividend taxation (8.75% for basic-rate earners, 33.75% for higher-rate earners, and 39.35% for additional-rate earners) following the £500 annual dividend allowance.
For investors managing broader commercial operations, combining property portfolios with tax strategies like the Seed Enterprise Investment Scheme can offer alternative mechanisms for tax-efficient capital growth.
Underwriting Criteria and Director Personal Guarantees
Although the borrowing entity is a limited company, specialist lenders underwrite the human directors and shareholders behind the corporate veil.
1. Personal Guarantees (PGs)
Almost all UK commercial lenders require an irrevocable Personal Guarantee from every director and significant shareholder (normally defined as anyone holding 20% to 25% or more of share capital). In executing a personal guarantee, you become personally liable for the mortgage debt, accrued interest, and legal costs if the company defaults and property repossession fails to clear the outstanding balance.
2. Minimum Personal Earned Income
Many specialist lenders require at least one director to demonstrate minimum personal earned income of £25,000 per year outside of rental turnover. This reassures underwriters that directors have independent income to cover unforeseen void periods or maintenance spikes. However, a growing tier of specialist lenders now accepts experienced landlords with zero minimum earned income requirements.
3. Portfolio Landlord Rules
Under Prudential Regulation Authority regulations, any investor holding four or more mortgaged rental properties (whether owned personally or inside limited companies) is classed as a “portfolio landlord.” Underwriters must review your entire property portfolio, inspecting total portfolio gearing, cash flow coverage, and regional tenant concentration before approving additional lending.
To optimize commercial balance sheets and fleet logistics alongside property holdings, review options for business vehicle finance or cash acceleration through invoice discounting facilities.
Transferring Existing Personally Owned Property into an SPV
Investors holding residential rental properties in their personal names frequently inquire about transferring their existing portfolios into a limited company. While mathematically appealing from an ongoing income tax perspective, transferring existing property is legally treated as a sale from the individual to the company at full market value.
This transaction triggers two substantial tax hurdles:
- Capital Gains Tax (CGT): You must pay CGT on the capital growth achieved since the property was originally purchased, calculated against current market value.
- Stamp Duty Land Tax (SDLT): The purchasing company must pay the full commercial SDLT rates, including the 5% higher rate surcharge, on the full market value of each property.
While Section 162 Incorporation Relief can defer Capital Gains Tax if an investor can prove they are running a substantive property business (typically demanding 20+ hours per week of personal management without third-party letting agents), Stamp Duty remains payable in almost all residential situations unless a qualifying partnership structure existed previously. For most single-property landlords, transferring existing assets is prohibitively expensive; the SPV route is best applied to all fresh property acquisitions.
Frequently Asked Questions
Can a brand new SPV get a limited company mortgage?
Yes, specialist lenders routinely advance mortgages to newly incorporated SPVs that have zero trading history or assets. The lender’s underwriting decision relies on the projected rental income of the property being purchased and the personal credit history and income of the company directors.
What is the maximum Loan-to-Value (LTV) for a limited company mortgage?
Most specialist lenders offer limited company mortgages up to 75% LTV, meaning you need a minimum 25% deposit. A select number of providers offer 80% LTV facilities, though borrowing at 80% LTV carries higher interest rates and stricter rental stress test requirements.
Can an existing trading company get a buy-to-let mortgage?
While a few specialist lenders offer mortgages to trading companies, the choice of products is narrow and interest rates are significantly higher. Most property investors establish a brand new SPV solely for property holding, funding the purchase deposit via an intercompany loan from their trading company.
How long does a limited company mortgage application take?
From initial application to legal completion, a limited company buy-to-let mortgage typically takes between six and ten weeks. The process involves specialist legal representation, independent legal advice for director personal guarantees, and property valuation surveys.
Do all shareholders need to sign a personal guarantee?
Lenders universally require personal guarantees from all directors and major shareholders holding 20% to 25% or more of the company’s shares. Minor shareholders holding under 20% equity are generally exempt from personal guarantee requirements.
What happens if I want to sell a property held in an SPV?
You have two choices: you can sell the physical property asset directly (repaying the mortgage and paying Corporation Tax on the net capital gain), or you can sell the entire company (shares of the SPV) to another property investor. Selling the company shares can be highly attractive to buyers because they pay 0.5% Stamp Duty on shares instead of up to 5% to 15% Stamp Duty Land Tax on physical property.
The Bottom Line: How to Proceed
A limited company mortgage represents the most tax-efficient structure for UK property investors building long-term, multi-property buy-to-let portfolios. By neutralizing Section 24 mortgage interest relief restrictions and unlocking more flexible 125% rental stress testing, the SPV model allows landlords to retain substantial profits and accelerate equity compounding.
However, corporate property ownership requires professional preparation. Ensure your company is incorporated with the correct property SIC codes, budget for higher arrangement fees and annual accountancy costs, and discuss your personal dividend strategy with a qualified accountant. By combining disciplined property sourcing with an optimized SPV structure, you establish a resilient commercial foundation for enduring portfolio wealth.